


Fully integrated, multi-specialty dental platform for sale
Short description
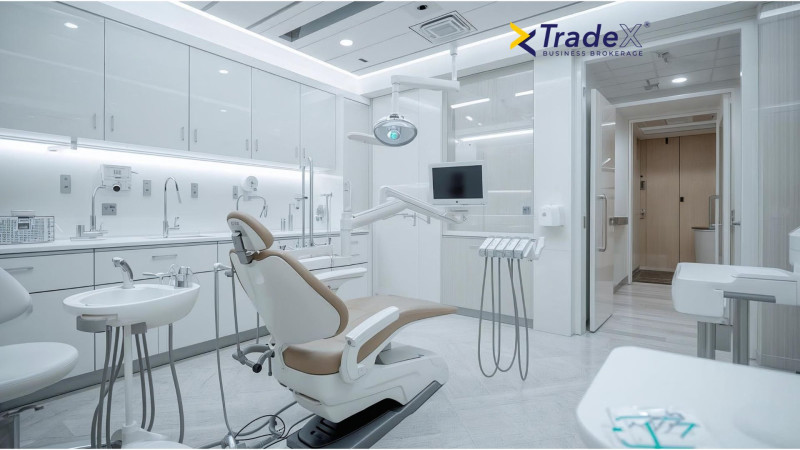
A fully integrated, multi-specialty dental platform with limited owner revenue dependency. Two established sites with several treatment rooms, complete specialty coverage, digital radiology performed on site and an owned CAD/CAM dental laboratory: a degree of integration normally found only in operators with ten or more clinics.
Products and Services
Complete coverage of every major specialty in one place — implantology, prosthetics, orthodontics, oral surgery, endodontics under microscope, periodontology, pedodontics and prophylaxis. A complex case is completed without referral out, prosthetic work is produced in the group’s own laboratory and imaging is performed on site, so the group captures the full case value rather than a share of it.
Operations
Scalable operating model with the following features:
• Premises: Three locations: two clinics with several treating rooms, and a fully equipped lab
• Staff: Lean core team, with specialists on revenue-share; the largest cost category is variable.
• Process: Standardized procedures across sterilization, patient flow, radiology and complaints;
• Compliance: full regulatory stack held and current, no litigation reported
• Systems: Cloud platform captures appointments, treatments, plans and receipts, automates treatment-based recalls and reconciles extracts to the financial statements.
Why this one clears the usual screens
• Revenue does not leave with the seller: clinical work delivered by a team of specialists; owner’s role is supervisory, while patient relationships, records and recall rights remain with the company.
• The numbers are verifiable upfront: both operating entities file annual accounts, and filed turnover matches three years of management accounts.
• The margin is structural: owned prosthetic production and imaging retain value inside the group instead of paying it to external providers.
• Growth requires no capital: at 63% chair occupancy, existing chairs and team capacity can support higher utilization.
• The downside is protected: the business has no debt or shareholder loans and collects about 95% of fees on treatment completion.
What makes a difference
• Imaging and prosthetic production are owned, not bought. The business has in-house radiology and its own laboratory.
• Speed follows from ownership. The vertical integration compresses diagnosis to treatment and keeps margins.
• Recurring patient base: 76% of patients treated in the last twelve months were returning patients.
• The laboratory is a business, not a cost center. More than 50% of revenue comes from external work.
• Long established brand with strong patient trust. Long tenure, minimal patient acquisition cost, favorable reviews create credibility that cannot be bought quickly.
• The brand has already been shown to transfer. Patient attachment sits with the institution rather than clinicians.
• Financing is matched to the case mix. The bank instalment facility supports high-value procedures.
• The regulatory stack is hard to replicate quickly. Three-to-five-year replication barrier for competitors.
Market and development potential
Romania averages 0.3 dental consultations per capita per year against a Western European norm above 1.0, so growth comes from activating non-attenders rather than taking share. The market is extremely fragmented, with several hundreds of operators in county alone and no scaled local champion. Case mix is already moving upmarket: surgery and orthodontics almost doubled over three years together reaching ~40% of revenue.
Growth does not require capital: meaningful capacity already exists within the current chairs, team and premises. Extended hours, an additional chair, chairside milling and corporate contracting sit beyond that — none of them reflected in current trading or in the asking price.
Investment Highlights
• EBITDA margin of over 28% against the 15%–25% typical of comparable Romanian dental businesses
• Strong multi year EBITDA and revenue growth
• EBITDA converts to cash almost immediately; approximately 95% of fees collected on completion
• Near Zero debt
• No capital needed for expansion
Detailed information
-

- Information
- Promoted business
Turnkey business - Ophthalmology services with 3 medical...
Sales business in the field of ophthalmology and medical optics, one of the first providers of...- Information
- 4.350.000 EURO Romania
-

Health / medical business search investors
Health Tourism Organizer & Medical Consulting / IPR Development company searching for investors...- Information
- 1.250.000 EURO N/A
-

Excellence in the Field – Medical Rehabilitation Clinic...
The business for sale is a well-established medical rehabilitation clinic with a strong portfolio...- Information
- 799.000 EURO Romania
-

Dental Practice for Sale in Romania - A Highly Profitable...
Dental practice for sale, with a constant profit, turnkey, in a field of interest for medical...- Information
- 1.000.000 EURO Târgu Mureș
-

Importer and distributor of medical equipment, devices and...
Profitable business: import and distribution of equipment, devices and supplies for aesthetic...- Information
- 8.500.000 EURO Romania
-

Network of clinics specialized in dental surgery and...
Profitable network of premium dental clinics with an experienced team, recurring patients, and...- Information
- 1.500.000 EURO Transilvania